
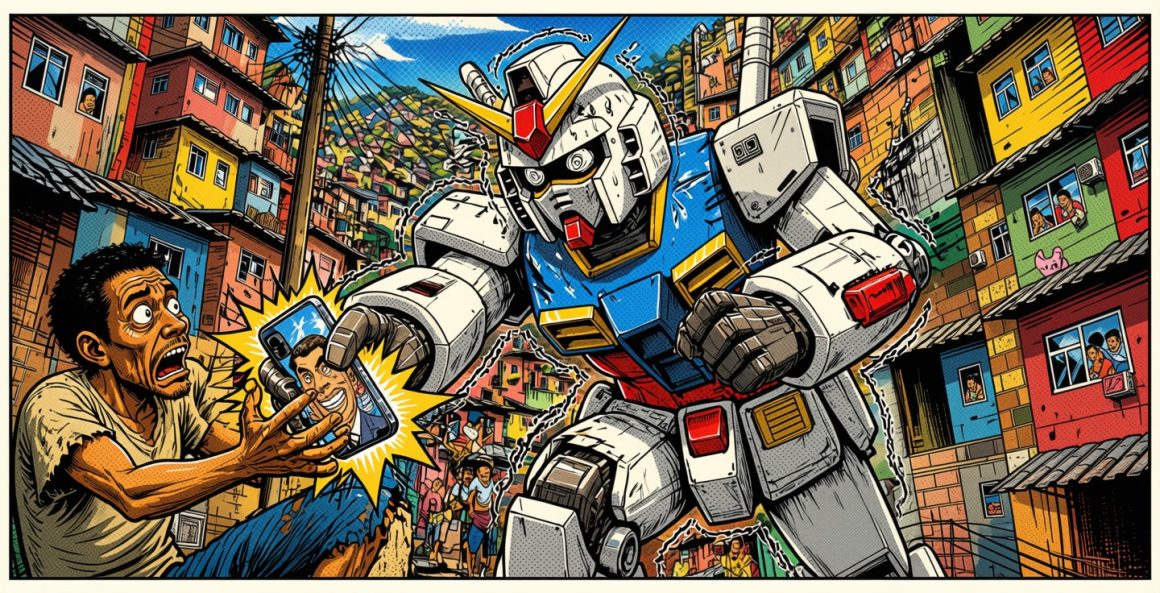
A $10 smartphone is a confusing thing: simultaneously too expensive and too cheap.
The GSMA’s latest numbers show Sub-Saharan Africa wrestling with this Schroedinger’s smartphone problem. For the poorest fifth of the region’s population, an entry-level internet-enabled handset costs 76% of average monthly income. Bring the price under $10 and the GSMA estimates around 580 million more people could afford one. Even then, 240 million still couldn’t.
“There’s only so low you can go in hardware costs, and how low you need to get is lower than that,” says Claire Sibthorpe, Head of Digital Inclusion at the GSMA.
While that sounds like tough commercial luck, a lack of a usable connection excludes people from opportunity in ways which are deeply felt. Having no device means uneven access to information; to services; to finance; to advice; and, these days, to AI-powered services too. And across the globe the people who most need those kinds of services are the least able to access them.
Sibthorpe’s team has just published The State of Mobile Internet Connectivity 2026, the association’s annual audit of who is online, who isn’t, and why. 3.4 billion people still don’t use mobile internet, and 3.1 billion of them live within range of a mobile broadband network. Coverage is no longer the problem; only 3% of the world’s population lives outside it, and that’s dropping all the time as satellite services proliferate.
The barriers, then, are on the user’s side. The GSMA surveys people every year on what stops them going online, and the answer rarely changes.
“When we look at the state of digital inclusion, we always also look at the barriers,” Sibthorpe says. “It comes out every year: the top barrier, if you average it across low-income countries, but also especially Africa, is handset affordability.”
Total Recall
This year’s report arrives with an unwelcome new variable. The data centres being built for AI are consuming memory at a rate that has upended the component market. According to the GSMA, memory prices more than doubled between Q3 2025 and Q1 2026, then rose a further 80–90% in Q2 2026. At the bottom of the market, memory is now close to half the bill of materials for an entry-level smartphone.
The effect took a while to show up in shops. “Prices went up at the end of last year because of the memory prices, but a lot of partners had a stock of phones,” Sibthorpe explains. “So it wasn’t hitting retail prices at that point. But now it’s starting to hit retail prices, and it’s starting to hit what phones are out there.”
Omdia reports African smartphone shipments falling 7% year on year in Q2 2026, the first decline in three years, while sub-$100 shipments dropped 34%. Average selling prices rose $41 to $202. Omdia expects the African market to shrink 26% across 2026. IDC forecasts a 13.9% global decline and warns that the sub-$100 segment risks becoming “economically unviable.”
None of that is in this year’s inclusion figures yet. The report counts 160 million people coming online in 2025, down from 190 million in 2024: a slowdown of around 16% that predates the price shock. Sibthorpe expects “the real impact of these price increases” to show in next year’s edition.
There’s an irony here. AI is the reason governments are paying fresh attention to inclusion, because “to get the benefits of AI, you need to be digitally included.” But it is “also driving up costs that are making it even harder.” The GSMA’s Director General, Vivek Badrinath, put it more bluntly: “AI is meaningless if people cannot get online in the first place.”
Bargaining Chip
A year ago the GSMA was talking about price targets. A $30 handset would have been affordable for 1.6 billion more people globally; a $20 one for 2.2 billion. Early this year a coalition of African operators including Airtel, MTN, Orange and Vodacom announced pilots of $40 4G smartphones in six markets.
However, Rest of World notes that memory costs rose from 10–15% of such a phone’s bill of materials to 30–40%. The GSMA now says the $20 and $30 targets are increasingly out of reach.
The industry has tried to deliver budget options before, and they have had their own problems. India’s Freedom 251, a phone promised at around $4, collapsed amid fraud allegations. Mozilla’s $25 Firefox OS phones and Google’s Android One struggled against better Chinese handsets at slightly higher prices.
Sibthorpe’s point is more fundamental, though. Even a successful ultra-low-cost phone can’t reach everyone, because the price at which the poorest can afford a device is below what anyone can make one for. “Reducing hardware costs will not get us to where we need to get to,” she says. “It’s always going to be a combination of approaches: trying to get as low as you can on the device costs, but also having to layer these other things as well.”
What are those other things? Most have been tried somewhere, and the results are informative but frustrating.
Handset Handout
The most direct option is for the state to buy phones and hand them out. There’s an economic case for it: the GSMA estimates that closing the mobile usage gap would add $3.5 trillion to global GDP between 2023 and 2030, more than 90% of it in low- and middle-income countries. It’s not quite that straightforward, though.
Take the Indian state of Chhattisgarh. In 2018 its government announced the distribution of more than two million free smartphones, mostly to female heads of household, while building new cell towers and offering free data. The following year a new government halted the scheme and ordered an audit of handset quality and procurement, reportedly leaving around 900,000 phones in warehouses. Researchers from Yale and IDinsight tracked the recipients. The scheme initially reversed the gender gap in smartphone ownership… but five years later, many women had lost their phones to men in the household and the gap in usage had widened again. An additional digital literacy programme did more to increase women’s use of smartphones.
Rajasthan tried the same thing in 2023, targeting four million women in its first phase. It was put on hold after the state election that December.
These echo a more famous effort. One Laptop Per Child promised a $100 laptop for every child in the developing world, launched to fanfare at Davos in 2005. The price ended up closer to $200. A ten-year randomised study in rural Peru found no effect on children’s maths or reading scores. It did find they became very good at using the laptops.
The lesson isn’t that devices don’t matter. Uruguay’s version of the one Laptop Per Child programme, Plan Ceibal, measurably narrowed the income gap in household computer ownership and internet use. So handouts can close access gaps, but on their own they don’t deliver the outcomes they planned; and when they are tied to an election cycle, they tend not to outlast it.
Taxing Times
A less glamorous lever has a better record. In April 2025, South Africa removed its 9% excise duty, a luxury tax, on smartphones priced under R2,500. The GSMA’s study of the change, published in July this year, estimates it led to around 1.1 million additional entry-level smartphone sales over the following year and reversed a steady decline in that segment.
“Reducing some tax, especially targeting those lower-income phones, can make a difference,” Sibthorpe says.
There is independent support for that. While Omdia’s Q2 2026 figures show Nigeria, Kenya and Egypt’s smartphone markets shrinking, South Africa’s grew 17%. Tax relief is also, in effect, a subsidy that needs no procurement, distribution list or warehouse, and so avoids most of the ways handout schemes went wrong.
The GSMA’s Handset Affordability Coalition is now urging African governments to drop taxes on devices under $100. However, extra sales are not the same as new internet users. Some buyers will be upgrading from feature phones; it is still progress, but finance ministries will want to have a clear idea of what giving up tax revenues will buy them.
Not every policy is pulling in the same direction. Nigeria is rolling out a device management system that registers every handset’s IMEI in order to block counterfeit and stolen phones. All well and good, but they are charging a registration fee on each device. As a fixed fee, that affects the price of the cheapest phones the most.
Second Hand News
If new phones are getting dearer, what about old ones? The GSMA’s own launch statement calls on the industry to “ease reuse of devices.” The UK government estimates that more than 200 million unused devices are sitting in British homes, which could make a huge difference.
Sibthorpe is cautious though. “Refurb is an area that can be considered,” she says, “but the reality at the moment is that a lot of the refurb phones are more the high-end ones. How do you make it economical to have the lower-end ones refurbished, and how do you ensure the quality?”
The market bears her out. Counterpoint puts Apple’s share of the global refurbished smartphone market at 58%. Refurbishment works where a used premium device is still worth enough to justify testing, repair, warranty and shipping. A three-year-old entry-level Android phone rarely clears that bar, and it’s more likely to use software that no longer gets security updates.
There’s an element of image to consider, too. Shipping rich countries’ old handsets to poorer ones sounds like a neat solution until it’s described as exporting e-waste, which is how critics tend to describe it. There is a huge market for re-used devices, but it is a better answer for the middle of the market than for the bottom.
Lock, Stock
For anyone used to European mobile markets, the obvious fix is to spread the cost with different operator financing models. If people can’t afford a phone as a one-off cost, that’s exactly what many people find in Europe today… and yet they can walk out of a phone shop without paying anything for their device.
The European model doesn’t transplant easily. Handset contracts usually rely on a monthly billing relationship, a credit check and a steady income to pay off the phone. In Kenya, 98% of mobile subscriptions are prepaid. Most customers have no credit file with a bank, earn irregularly, and pay for airtime in local currencies while handsets are priced in dollars.
So emerging markets have built something different. Lenders secure the loan with the phone itself, which they can lock remotely if payments stop. Customers repay in small daily or weekly amounts through mobile payments. Safaricom’s Lipa Mdogo Mdogo (“pay little by little”) had 500,000 active customers paying for handsets this way by 2022. M-KOPA reports 4.8 million customers in Kenya and more than a million in Nigeria. PayJoy says it has passed 20 million across emerging markets.
It works at scale, and it reaches people banks won’t. But there are some concerns. If governments view this as an essential device, increasingly the gateway to money, work and government services, should the lender be able to switch it off? Meanwhile, customers have complained publicly about phones staying locked after making their last payment. Ofcom now requires UK operators to tell customers when their handset is paid off and to stop charging for it. Comparable protections for locked-device financing elsewhere are thin.
There’s also a question of who it helps. Omdia notes that vendors are using financing to move buyers up into the $120–150 price bands. That helps people near the affordability line more than the poorest. Financing lowers the upfront payment; it doesn’t lower the price.
Question Time
None of these levers is enough on its own, and that’s the point Sibthorpe keeps coming back to. Tax cuts, subsidies, financing, reuse and ultra-low-cost devices each pull on different levers which can help. Governments, manufacturers, lenders and operators each control one or two of them. “It’s not an easy thing,” she says. “Otherwise it would have been solved.”
Asked for a single priority, though, she doesn’t hesitate. “If we can get affordable internet-enabled handsets into the hands of people, I think that will probably make the biggest difference, because I think that’s the hardest thing. Once that’s out there, we can build skills, we can have relevant content.”
This leads us to a few outstanding questions:
- If the price the poorest can pay is below what any manufacturer can build for, who covers the difference, and through which channel?
- Can consumer protection apply to locked-device financing without killing the model that makes it possible?
- And as AI purchases soak up the available memory for, will anyone at the top of the value chain think about the people at the far end who are being priced out of being customers?
TelcoForge will return to two related threads in the coming weeks: how the digital divide in emerging markets compares with the one richer countries are trying to solve with 6G, and the forces reshaping the low end of the device market. If you have a perspective to add or additional information to share, get in touch.